The Paper Trail: Insuring Your Jordan Rotation in 2026 Without the Policy Panic
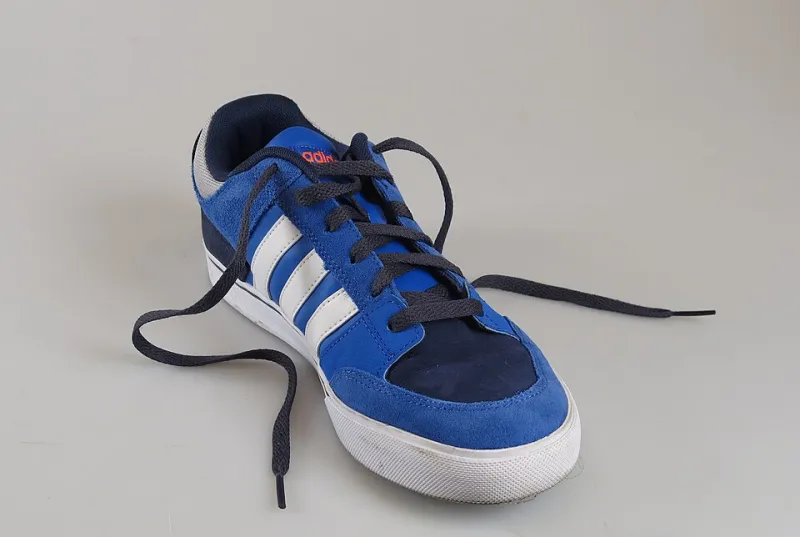
Photo: Adidas (fabrikant), Public domain, via Wikimedia Commons
There’s a particular kind of UK fear that arrives when the heating clicks off, the flat goes quiet and you realise the boiler has chosen violence. For most people, the panic is about the repair bill. For a Jordan collector, there’s a second wave: what happens to the rotation if the worst actually happens?
Home insurance is not the sexiest corner of sneaker culture. It doesn’t get raffle hype or resale graphs. But if your collection has moved beyond a couple of beaters by the door, it deserves more than a vague assumption that “the house insurance will sort it.” In 2026, with prices wobbling, resale platforms shifting and specialist sneaker cover becoming more visible, the smart move is to treat protection like part of the care routine — alongside the suede brush and the box storage.
Start With the Number, Not the Vibe
Most underinsurance starts with a feeling. You look at the shelf, think “that’s probably a couple of grand,” and move on. The problem is that insurers deal in specifics, not vibes.
Value your collection pair by pair. Note the model, colourway, size, condition and whether you’ve kept the box, laces and receipt. Then decide which number actually matters: replacement value, current resale value or what you paid. For insurance purposes, “new for old” cover usually points toward replacement, but sneakers are awkward because some pairs can’t be replaced at all. A general release AJ1 Low might be easy to source. A limited regional drop with a battered box and no paperwork is a different conversation.
Use sold listings rather than asking prices. Check a few UK-based sources, note the date, and keep screenshots. If you have deadstock pairs, value them as deadstock. If you wear them, be honest about condition. A spreadsheet is fine; a notes app works too. The point is to have a defensible figure rather than a number pulled from the air after a stressful phone call.
The Receipts Are the Rotation
Documentation is where UK collectors often get caught out. We’re good at keeping boxes. We’re less good at keeping proof.
Take clear photos of each pair: side profile, tongue tag, size label, box label and any receipts or invoices. A short video walking through the shelf can be surprisingly useful because it shows the collection as a whole, not just individual pairs. Store it in the cloud, not only on the phone that goes everywhere with you. If you’ve bought from a reseller, keep the order confirmation. If you’ve bought from a mate, write down the details while you both remember them.
Boxes matter here, too. Not just because UK heads treat cardboard as part of the pair, but because box labels, tissue and accessories help prove condition and completeness. If a claim ever happens, “I had the box” sounds a lot stronger when you can show it.
Where Standard Cover Trips
A standard home contents policy can cover shoes, but that doesn’t mean it will cover your collection in the way you expect. Watch for single-item limits, total limits for valuables, and optional accidental damage cover that may not be switched on. Check whether items are covered away from home, because a weekend trip or a matchday carry is exactly when things go missing.
Then there’s the language. Insurers may classify sneakers as clothing or footwear, which can affect how claims are assessed. Theft from a car, shed or communal hallway may be excluded or heavily restricted. Gradual wear and tear, creasing, yellowing and sole separation are not sudden losses. And “mysterious disappearance” is rarely the friendly phrase it sounds like.
Underinsurance is the quiet killer. If you insure £8,000 worth of pairs for £3,000, some policies may reduce a payout proportionally rather than simply paying the limit. That’s the bit worth reading twice. Also check the excess: claiming for a £90 pair might cost you more in hassle and future premiums than it’s worth.
When Specialist Cover Earns Its Keep
Specialist sneaker insurance isn’t automatically necessary for everyone. If you have five wearable pairs, a standard contents policy with the limits checked may be perfectly reasonable. But if your collection is high-value, heavy on deadstock, frequently travelling to events, or part of a side hustle, a specialist policy can make sense.
Compare what’s actually covered, not just the monthly price. Ask about storage requirements, whether boxes and accessories are included, how claims are valued, and what happens if a pair can’t be replaced. Read the exclusions with the same energy you’d give a drop-day terms page. If a policy demands a locked room and you live in a shared flat, it’s not the policy for you.
The Box Room Test
Once a year, do a quiet audit. Update your spreadsheet, re-check your policy limits, and tell your insurer if the collection has grown significantly. Keep photos current. Don’t leave the only record of your grails in a group chat.
Insurance won’t make you love the collection more. But it stops the rotation being a gamble you didn’t know you were taking. In 2026, the paper trail is part of the pair.